Global PC shipments plunge 20 % as shortages push up prices
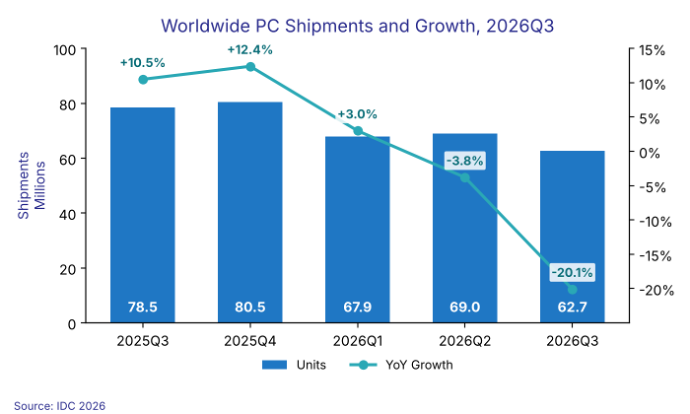
Worldwide PC shipments fell by one-fifth from a year ago in the third quarter of 2026, as supply shortages and rising prices weakened demand. Shipments also dropped compared with the second quarter, breaking the usual pattern where the third quarter is stronger. It was the second consecutive quarterly decline.
According to research firm IDC, shipments fell 20.1% from a year ago to 62.7 million units during the quarter, down from 78.5 million a year earlier. The decline was significantly steeper than the 3.8% drop recorded in Q2, while shipments also fell 9.1% sequentially—an unusual development for a quarter that normally benefits from back-to-school season demand.
IDC blames the slump mostly on early stockpiling. Earlier this year, PC makers and sellers bought up extra stock to get ahead of price hikes tied to memory costs. That boosted shipments during the first half of the year but effectively borrowed demand from the second half, leaving the third quarter with little room for the usual seasonal increase.
The situation is being compounded by elevated PC prices. IDC says supply problems and rising costs due to the AI data-center buildout are among the main factors weighing on the market.
Distributors are now trying to sell through that extra inventory while facing high prices that discourage buyers. Some short-term promotions are possible, but prices are expected to stay well above last year’s levels in the near term. Most likely, conditions will only get worse before they improve—prices are expected to remain well above year-ago levels for the rest of 2026 and into 2027.
With macro conditions worsening, the risk is that the outlook for the next few quarters gets worse before it gets better, - Jitesh Ubrani, research director for consumer devices at IDC.
The decline affected all major PC manufacturers, although some companies fell faster than others. Lenovo remained the market leader with 14.9 million shipments and a 23.8% share, despite a 22.6% year-over-year decline. HP Inc. suffered the steepest fall among the top five, with shipments down 30.9%, while Dell fell 25% to 7.6 million units. Apple was comparatively resilient, with shipments declining only 11.3% to 5.9 million units, while Asus shipped 5.5 million PCs, down 8.6%.
| Company | 3Q26 Shipments (mln) | 3Q26 Market Share | 3Q25 Shipments (mln) | 3Q25 Market Share | 3Q26/3Q25 Growth |
| 1. Lenovo | 14.9 | 23.8% | 19.3 | 24.6% | -22.6% |
| 2. HP Inc | 10.3 | 16.5% | 15.0 | 19.1% | -30.9% |
| 3. Dell Technologies | 7.6 | 12.1% | 10.1 | 12.9% | -25.0% |
| 4. Apple | 5.9 | 9.5% | 6.7 | 8.5% | -11.3% |
| 5. ASUS | 5.5 | 8.7% | 6.0 | 7.6% | -8.6% |
| Others | 18.4 | 29.4% | 21.4 | 27.3% | -14.0% |
| Total | 62.7 | 100.0% | 78.5 | 100.0% | -20.1% |
Lenovo, HP and Dell together lost 4.2 percentage points of market share compared with a year earlier, as their shipments declined faster than the overall market. Apple and Asus, meanwhile, increased their respective shares despite lower shipment volumes.
Source(s)
 Add as a preferred source on Google